The Ledger Remembers: Client Money Controls for Audit-Ready UK Practices
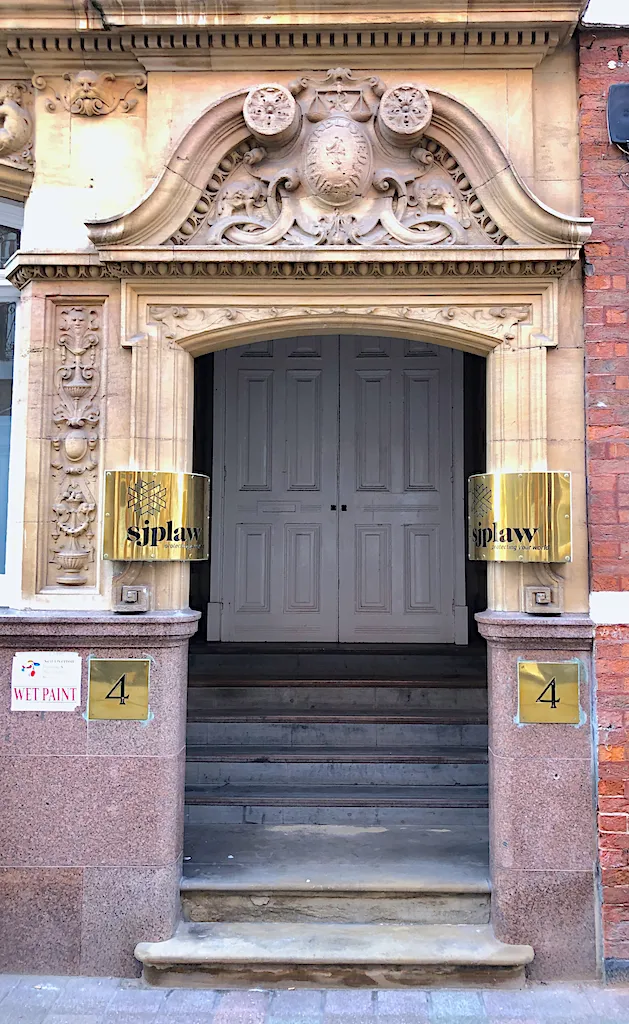
Photo: Paul Harrop , CC BY-SA 2.0, via Wikimedia Commons
Client money is rarely the most glamorous subject in a professional practice, but it is one of the most revealing. A firm's controls over client funds say a great deal about its discipline, its governance and its readiness for scrutiny. Under the SRA Accounts Rules and equivalent regimes across the UK professional services sector, the obligations are not merely administrative. They are protective. They exist because client money is held in a position of trust, and because trust is easier to preserve through systems than through good intentions.
For practices in Leeds, London and beyond, the risk is not usually deliberate misappropriation. It is the quiet accumulation of small departures from procedure: a transfer made without a bill, a reconciliation deferred by a week, a residual balance left unexplained, a third-party managed account opened without the right checks. Each may appear minor in isolation. Together they form the kind of pattern that regulators treat as a control failure.
The meaning of segregation in practice
The central principle is straightforward: client money must be kept separate from the firm's own money. That means a client account, properly designated, and office account arrangements that do not allow the two to blur. Segregation is not achieved by labelling alone. It requires payment controls, authorisation limits, clear descriptions on bank statements and a discipline around transfers that is understood by everyone who touches the ledger.
A common breach scenario is the informal transfer. A fee earner instructs accounts to move money from client to office account before a bill has been issued, on the understanding that a bill will follow. If the bill does not follow promptly, or is disputed, the firm has used client money for its own purposes. The amount may be small; the principle is not. The remedy is procedural: transfers only against a valid bill or other permitted ground, with documented authorisation and a clear audit trail.
The second scenario is the residual balance. A matter closes, a small sum remains, and no one quite knows whether it belongs to the client, a third party or the firm. Left unaddressed, the balance sits in the client account and becomes a recurring exception. A disciplined practice treats residuals as a live issue, not a dormant one: investigate promptly, document the reasoning, repay where possible and escalate where not.
Reconciliation as a governance habit
Reconciliation is often treated as a month-end chore. It is better understood as a governance habit. The SRA Accounts Rules require client account reconciliations at least every five weeks, with records kept of the reconciliation and any differences. The precise timetable matters less than the discipline: bank statements reconciled to client ledger balances, individual client balances checked, and differences investigated rather than carried forward.
Where reconciliations fail, the failure is usually organisational rather than technical. A busy accounts team may rely on one person; a multi-office practice may operate local ledgers without a central view; a suspense account may become a holding pen for items nobody has time to resolve. In each case, the answer is not simply more effort at month end. It is a control framework: named responsibility, a fixed timetable, dual review for exceptions and a clear escalation route to the compliance officer for finance and administration, or equivalent.
A useful test is whether the firm could explain its client account position to an inspector at short notice. If the answer depends on one individual's memory, the control is fragile.
Third-party managed accounts: convenience with conditions
Third-party managed accounts can be a sensible arrangement for firms that wish to reduce the operational burden of holding client money. But they are not a route to less governance. The SRA's rules permit such accounts only where the arrangement is properly established and the firm satisfies itself that the account is managed by an authorised institution and meets the required conditions. The firm remains responsible for its own decisions about where client money is held and how the arrangement is monitored.
A frequent weakness is documentation. The bank agreement may be in place, but the firm's own record of approval, review and client communication may be thin. Another weakness is oversight: the firm assumes the third party is handling everything and stops checking. A disciplined approach includes periodic confirmation of the account's status, clear procedures for paying money in and out, and a documented rationale for using the arrangement. Convenience should never become a substitute for control.
The small failures that become findings
Regulatory findings rarely begin with dramatic dishonesty. They begin with ordinary administrative slippage. Consider these common scenarios:
- A disbursement is paid from the client account without a corresponding client ledger entry, leaving the ledger unexplained until the year-end audit.
- A client account is used to hold funds that should have been returned promptly, because the matter team has moved on and no one owns the residual.
- A bank reconciliation is signed off without review of old unpresented cheques, which later prove to be stale or duplicated.
- A fee transfer is made on a verbal instruction and documented after the event, leaving the audit trail dependent on recollection.
- A third-party managed account is used for a new matter without checking whether the arrangement covers that type of work or client.
In each case, the underlying issue is the same: the firm has allowed a shortcut to become a system. The remedy is equally consistent: define the control, assign the owner, record the evidence and review the exception.
A one-page controls checklist for 2026
Boards and management teams in Leeds and London can use a short checklist to test whether the client money framework is operating as intended:
- Is there a current written policy covering client account operation, transfers, withdrawals and residual balances?
- Are client and office accounts clearly segregated, with bank mandates and authorisation limits reviewed in 2026?
- Is a reconciliation completed at least every five weeks, reviewed by a second person and retained with supporting records?
- Are client ledger balances checked individually, not merely in aggregate?
- Are transfers from client to office account permitted only against a bill or other documented ground?
- Are residual balances reviewed at least monthly, with an owner and an action date?
- Are third-party managed accounts approved, documented and periodically reviewed?
- Are suspense accounts and unallocated receipts cleared promptly and escalated where necessary?
- Has the team received recent training on client money rules, including common breach scenarios?
- Does the board or management committee receive a concise client money report, with exceptions and remediation noted?
The standard is evidence
The regulatory standard is not simply honesty. It is evidence of control. A firm may hold client money with complete integrity and still fail to demonstrate that it has done so. The ledger remembers what memory forgets, and inspectors will follow the record.
For practices preparing for 2026 and beyond, the sensible course is to treat client money as a board-level discipline, not an accounts function alone. Segregation, reconciliation, third-party oversight and a clear exceptions process are not burdens imposed from outside. They are the marks of a practice that can be trusted with other people's money — and can prove it.